What is the market overview and scope of the Core Plug Market?
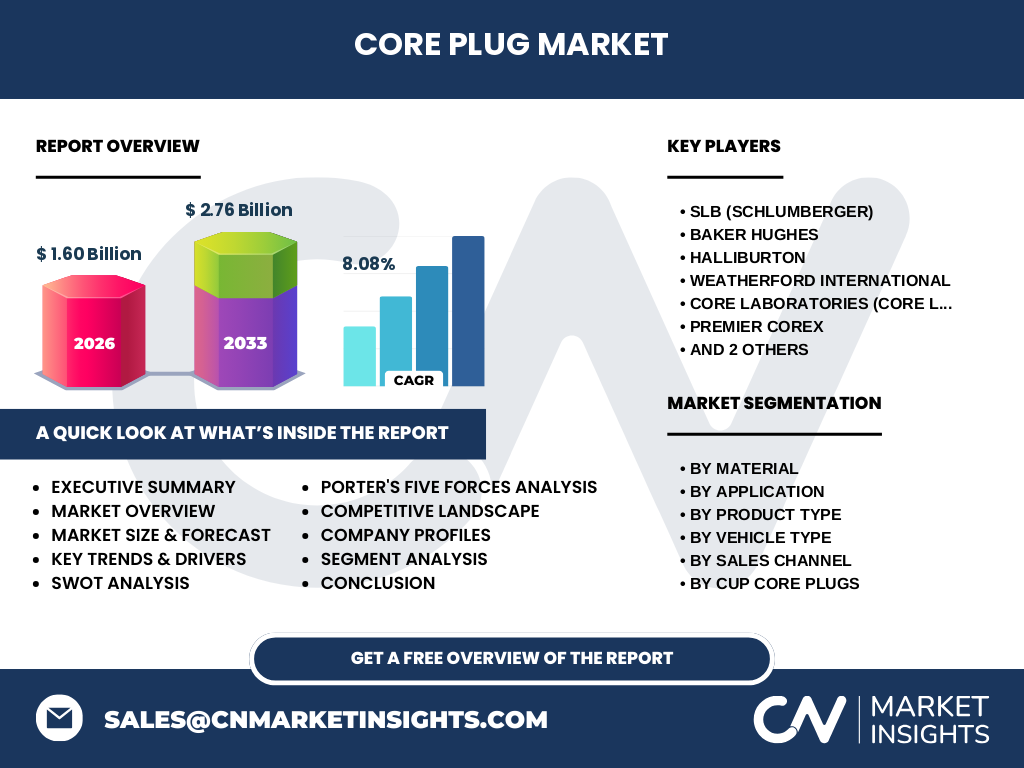
Our analysis indicates that the Core Plug Market encompasses vital engine sealing components essential for preventing coolant leakage in automotive and industrial blocks. Valued at 1.60 Billion in 2026, the industry serves critical functions across manufacturing hubs in Detroit and Hamburg, relying heavily on durable raw materials like cold-rolled steel, brass, and aluminum to withstand extreme thermal expansion and high-pressure operating environments.
What are the key market drivers, restraints, challenges, and opportunities in the Core Plug Market?
Structural growth is propelled by rising internal combustion engine production in emerging economies, though strict ISO and EPA emissions regulations present constant compliance hurdles. Supply chain volatility involving steel and aluminum pricing creates margin compression for suppliers. However, aftermarket demand for corrosion-resistant variants offers lucrative expansion pathways for agile component manufacturers targeting heavy-duty off-road machinery.
Emerging trends and growth patterns in the Core Plug Market
The shift toward advanced metallurgical coatings is redefining industry standards, with coated cup core plugs gaining traction due to superior galvanic corrosion resistance. Our research highlights that tier-1 suppliers are optimizing weight profiles through precision-engineered aluminum alloys, aligning with OEM lightweighting mandates across passenger and light commercial vehicle platforms to enhance overall fuel efficiency.
How did the COVID-19 pandemic impact the Core Plug Market and its recovery trajectory?
Pandemic-induced lockdowns severely disrupted automotive assembly lines and raw material logistics across major European and North American ports. Post-pandemic recovery has been characterized by aggressive inventory restocking and localized sourcing strategies, enabling the market to stabilize and pivot toward the projected 2.76 Billion valuation by 2033, driven by pent-up industrial machinery demand.
Competitive benchmarking and strategic dynamics in the Core Plug Market
The competitive landscape features a mix of specialized sealing manufacturers and diversified oilfield service giants like SLB (Schlumberger), Baker Hughes, and Halliburton, who apply high-pressure downhole sealing expertise to engineered components. Market concentration is moderate, with firms leveraging strategic distributor partnerships and proprietary welding technologies to secure long-term OEM contracts against regional fabricators.
Executive summary of the Core Plug Market
Our comprehensive report reveals a robust market trajectory, scaling from 1.60 Billion in 2026 to 2.76 Billion by 2033, representing a solid CAGR of 8.08%. Growth is anchored by resilient demand across automotive, marine, and agricultural equipment sectors, rewarding firms that prioritize metallurgical innovation and stringent quality control protocols required by global engine builders.
Market forecast from 2027 to 2033
Driven by sustained industrialization and commercial fleet modernization, the market is projected to expand from 2.76 Billion by the end of 2033 at a steady 8.08% CAGR. Sequential revenue acceleration will be most pronounced in Asia-Pacific and Latin American manufacturing corridors, fueled by increased capital expenditure in heavy commercial vehicles and off-road earthmoving equipment.
Segmentation analysis by material, application, product type, and sales channel
The market segments by material (Steel, Brass, Aluminum), application (Automotive, Marine, Industrial, Agricultural, Construction), product type (Flat, Domed, Cup, Weld In), vehicle type, and sales channel. Cup core plugs and steel variants dominate volume shares, while OEMs represent the primary sales channel, demanding exact dimensional tolerances governed by international manufacturing standards.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America and Europe maintaining mature, replacement-driven aftermarket demands, while Asia-Pacific acts as the primary volume engine due to massive automotive manufacturing output. Logistical proximity to major casting foundries dictates regional supply chain efficiency, giving localized producers a distinct cost advantage over overseas import alternatives.
In-depth regional review of manufacturing and consumption hubs
North American consumption is heavily weighted toward heavy-duty agricultural and construction equipment, whereas European markets enforce stringent environmental directives that favor advanced corrosion-resistant brass and coated steel plugs. Meanwhile, rapidly expanding industrial bases in China and India drive unprecedented consumption of standard flat and cup core plugs for commercial transport fleets.
Strategic positioning of leading companies in the Core Plug Market
Industry leaders such as Weatherford International, Core Laboratories (Core Lab), Premier Corex, Geotek Ltd, and OFITE Testing Equipment Inc leverage advanced laboratory testing and precision manufacturing to maintain competitive moats. Their strategic positioning focuses on high-integrity components designed for extreme pressure environments, ensuring high switching costs for OEM clients.
Porter's Five Forces analysis of competitive pressures
Supplier power remains moderate due to the commodity nature of raw steel and brass, while buyer power is high among major automotive OEMs capable of demanding strict volume discounts. The threat of substitutes is low given the irreplaceable mechanical function of core plugs, though intense rivalry among established players necessitates continuous R&D investment in proprietary coating technologies.
SWOT analysis of the Core Plug Market
Key strengths lie in mature manufacturing techniques and high mechanical reliability, offset by weaknesses such as raw material price sensitivity. Growth opportunities abound in electric vehicle thermal management integration and emerging market industrialization, while regulatory shifts toward alternative powertrains present a manageable long-term threat to traditional internal combustion applications.
Value chain analysis from raw materials to end-users
The value chain initiates with primary metal smelters supplying cold-rolled steel and brass coils, which are then stamped, formed, and treated by specialized component manufacturers. Finished plugs flow through tier-1 automotive suppliers and independent aftermarket distributors before reaching equipment repair shops, marine operators, and commercial vehicle maintenance fleets.
Investment insights and high-potential growth areas
Investors should target manufacturers specializing in corrosion-resistant and high-temperature variants, as these niche segments command superior margins. Strategic capital allocation toward automated stamping lines and localized distribution hubs in developing economies will yield the highest risk-adjusted returns throughout the forecast period ending in 2033.
Conclusion and key strategic takeaways
The Core Plug Market offers attractive expansion prospects, underpinned by an 8.08% CAGR pushing the market toward 2.76 Billion by 2033. Success in this sector requires balancing cost-competitive high-volume production with metallurgical innovations tailored to the rigorous demands of modern heavy-duty engines and industrial machinery.
Research methodology for baseline estimation and data triangulation
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with automotive tier-1 executives, and macroeconomic industrial output indices. This multi-layered validation process ensures high-fidelity market sizing, accounting for localized tariff fluctuations, raw material inflation, and shifting OEM procurement strategies.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics from 2026 to 2033, evaluating four core material types, five major end-use applications, and distinct regional manufacturing blocks. Analytical limitations include unforeseen geopolitical disruptions and sudden shifts in global trade agreements, which could temporarily alter raw material accessibility for component fabricators.
Recent developments, corporate announcements, and strategic moves
Recent industry activity is marked by increased merger and acquisition initiatives among specialized sealing providers and strategic capacity expansions by firms like SLB (Schlumberger) and Baker Hughes. Market leaders are actively forging long-term supply agreements with agricultural equipment manufacturers to secure predictable revenue streams amidst fluctuating commodity markets.